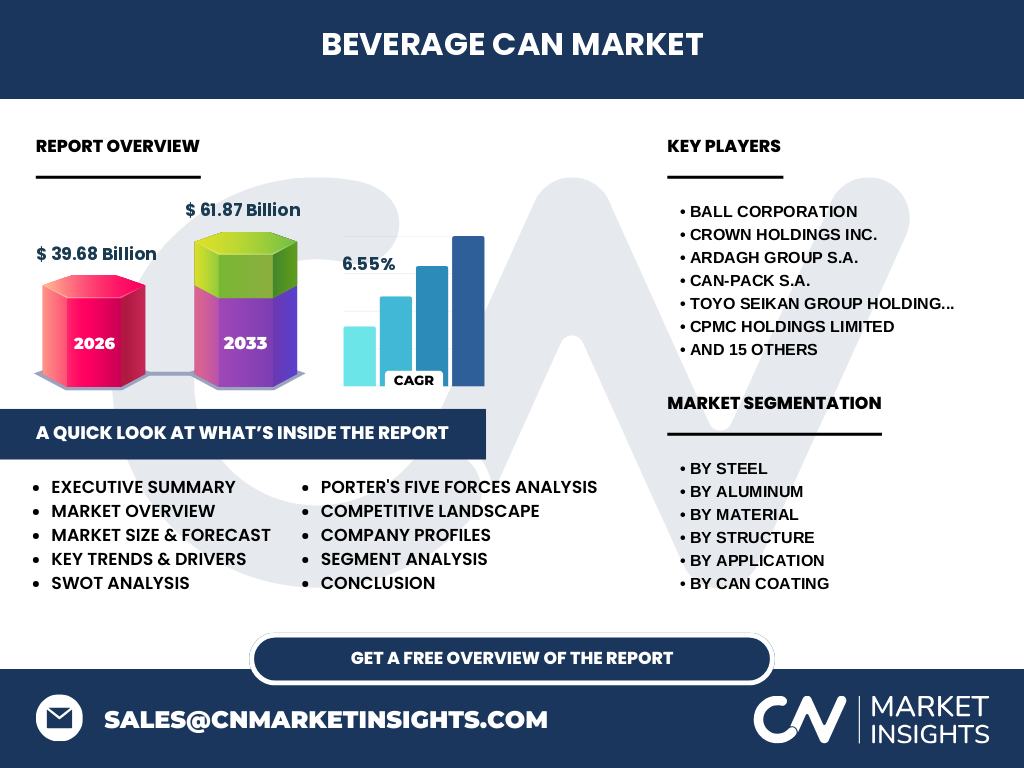
Market overview of the Beverage Can Market
Our analysis indicates that the Beverage Can Market is valued at 39.68 Billion in 2026. This sector encompasses rigid packaging solutions utilizing aluminum alloys like 3xxx and 5xxx series as well as steel substrates like tinplate. It plays a vital logistical role for global beverage brand owners navigating complex supply chains.
What are the key market drivers, restraints, challenges, and opportunities shaping the Beverage Can Market?
Growth is propelled by rising consumer preference for infinite recyclability over polyethylene terephthalate. However, volatile London Metal Exchange pricing for aluminum acts as a primary cost restraint. Regulatory pressures from bodies like the EPA create compliance challenges, while opportunities abound in lightweighting technology.
Structural Growth Drivers
The shift toward premiumization in craft carbonated soft drinks and functional sports beverages accelerates demand for two-piece aluminum cans. Brand differentiation through specialty finishes and digital printing allows manufacturers like Ball Corporation to capture higher margins in saturated retail environments.
COVID-19 impact analysis on the Beverage Can Market
Pandemic-era lockdowns caused unprecedented spikes in at-home consumption, straining supply chains for major producers like Crown Holdings Inc. Despite initial aluminum coil shortages and port bottlenecks, the industry rebounded swiftly as producers optimized domestic manufacturing footprints.
Competitive Benchmarking
The market features high consolidation among tier-one players including Ardagh Group S.A. and Toyo Seikan Group Holdings Ltd. These giants leverage vertically integrated operations and massive capital expenditure budgets to dominate global beverage filling contracts, squeezing smaller regional packaging converters.
Executive summary of the Beverage Can Market industry trends
Our research confirms the Beverage Can Market industry trends point to robust expansion, scaling from 39.68 Billion in 2026 to 61.87 Billion by 2033 at a CAGR of 6.55 percent. Sustainability mandates and circular economy initiatives serve as the core catalysts for this trajectory.
Market forecast for the Beverage Can Market from 2027 to 2033
Driven by rising disposable incomes and strict single-use plastic bans, the Beverage Can Market market size is projected to surge from 2027 to 2033. Achieving 61.87 Billion by the end of the forecast period requires continuous investments in high-speed, low-waste manufacturing lines.
Segmentation analysis of the Beverage Can Market
Our breakdown evaluates steel variants like tinplate alongside aluminum 3xxx and 5xxx series. Structural formats divide into two-piece and three-piece cans, serving applications from alcoholic beverages to fruit-based drinks, protected internally by epoxy or polyester coatings.
Regional market analysis and geographic distribution
Geographic performance varies significantly, with North America and Europe leading in per capita consumption due to established recycling infrastructures. Meanwhile, Asia-Pacific emerges as the fastest-growing region, fueled by expanding urban middle classes and aggressive capacity additions by players like Baosteel Packaging.
In-depth regional review of high-growth territories
Emerging economies in Southeast Asia and Latin America demonstrate accelerated demand for non-alcoholic and carbonated soft drinks in affordable two-piece cans. Local converters such as Envases Universales S.A. de C.V. are capitalizing on regional population booms and shifting retail landscapes.
Company profiles and strategic positioning in the Beverage Can Market
Industry leaders like Can-Pack S.A. and GZ Industries Limited differentiate themselves through localized production hubs and bespoke can coatings. Their strategic focus remains centered on securing long-term supply agreements with multinational beverage conglomerates to mitigate volume volatility.
Porter's Five Forces analysis of competitive intensity
Bargaining power of raw material suppliers remains moderate to high due to consolidated aluminum smelting operations. Threat of substitutes is mitigated by superior chilling speeds and UV protection offered by metal packaging over glass and plastic alternatives.
SWOT analysis of the Beverage Can Market
Core strengths include exceptional recycling rates and robust structural integrity. Weaknesses involve exposure to metal price fluctuations. Opportunities lie in developing lightweight composite materials, while threats stem from tightening environmental compliance standards governing internal epoxy linings.
Value chain analysis from raw materials to end-users
The value chain begins with bauxite mining and primary aluminum smelting, progressing to coil rolling, body maker forming, internal coating application, and high-speed filling. Logistics coordination via major freight corridors ensures timely delivery to final retail distribution centers.
Investment insights and high-potential areas
Investors should target greenfield manufacturing facilities in developing Asian markets and proprietary coating technologies compliant with emerging BPA-non-intent regulations. Capital allocation toward post-consumer recycling facilities secures feedstock and shields against primary metal inflation.
Conclusion and key takeaways for stakeholders
The Beverage Can Market analysis highlights a lucrative 6.55 percent CAGR pathway through 2033. Success in this market demands strict adherence to sustainability metrics, supply chain resilience, and continuous technological upgrades in can body reduction.
Research methodology for baseline estimates
Our research combines primary stakeholder interviews with C-level executives, trade registry data from aluminum institutes, and secondary macroeconomic indicators. Data triangulation ensures robust baseline sizing for the Beverage Can Market market size across all covered segments.
Scope of the report and coverage parameters
This report evaluates global trends, material categories, structural designs, and regional performance from 2026 to 2033. Macroeconomic disruptions, geopolitical trade tariffs on aluminum coil, and localized container deposit legislations are factored into our predictive modeling.
Recent developments in the Beverage Can Market
Recent strategic moves include joint ventures focused on closed-loop aluminum recycling and plant expansions by ShengXing Group Co Ltd. Furthermore, major producers are aggressively rolling out low-carbon beverage cans certified by the Aluminium Stewardship Initiative to meet corporate ESG targets.